
Kelly Bishop, Serving Van Alstyne, Anna & North Texas Buyers Since 2018
If you've been watching mortgage news the last few weeks, you've probably noticed the tone shifting. After a fairly calm summer, rates have started climbing again heading into fall — and if you're actively looking at homes in Van Alstyne or Anna, that's worth understanding before you set your budget, not after.
Where rates actually sit right now
The 30-year fixed has been drifting up through September, pushing past 6.7% on some daily surveys, with some economists warning it could touch 7% before year-end. The reasons are the usual mix — inflation staying sticky, Treasury yields climbing, and general uncertainty pushing investors toward safer bets, which indirectly pushes mortgage rates up too. None of this is a Van Alstyne or Anna problem specifically; it's a national rate story. But it lands differently depending on where you're shopping, and that's the part worth talking through.
Why this matters more in a growing area like Van Alstyne and Anna
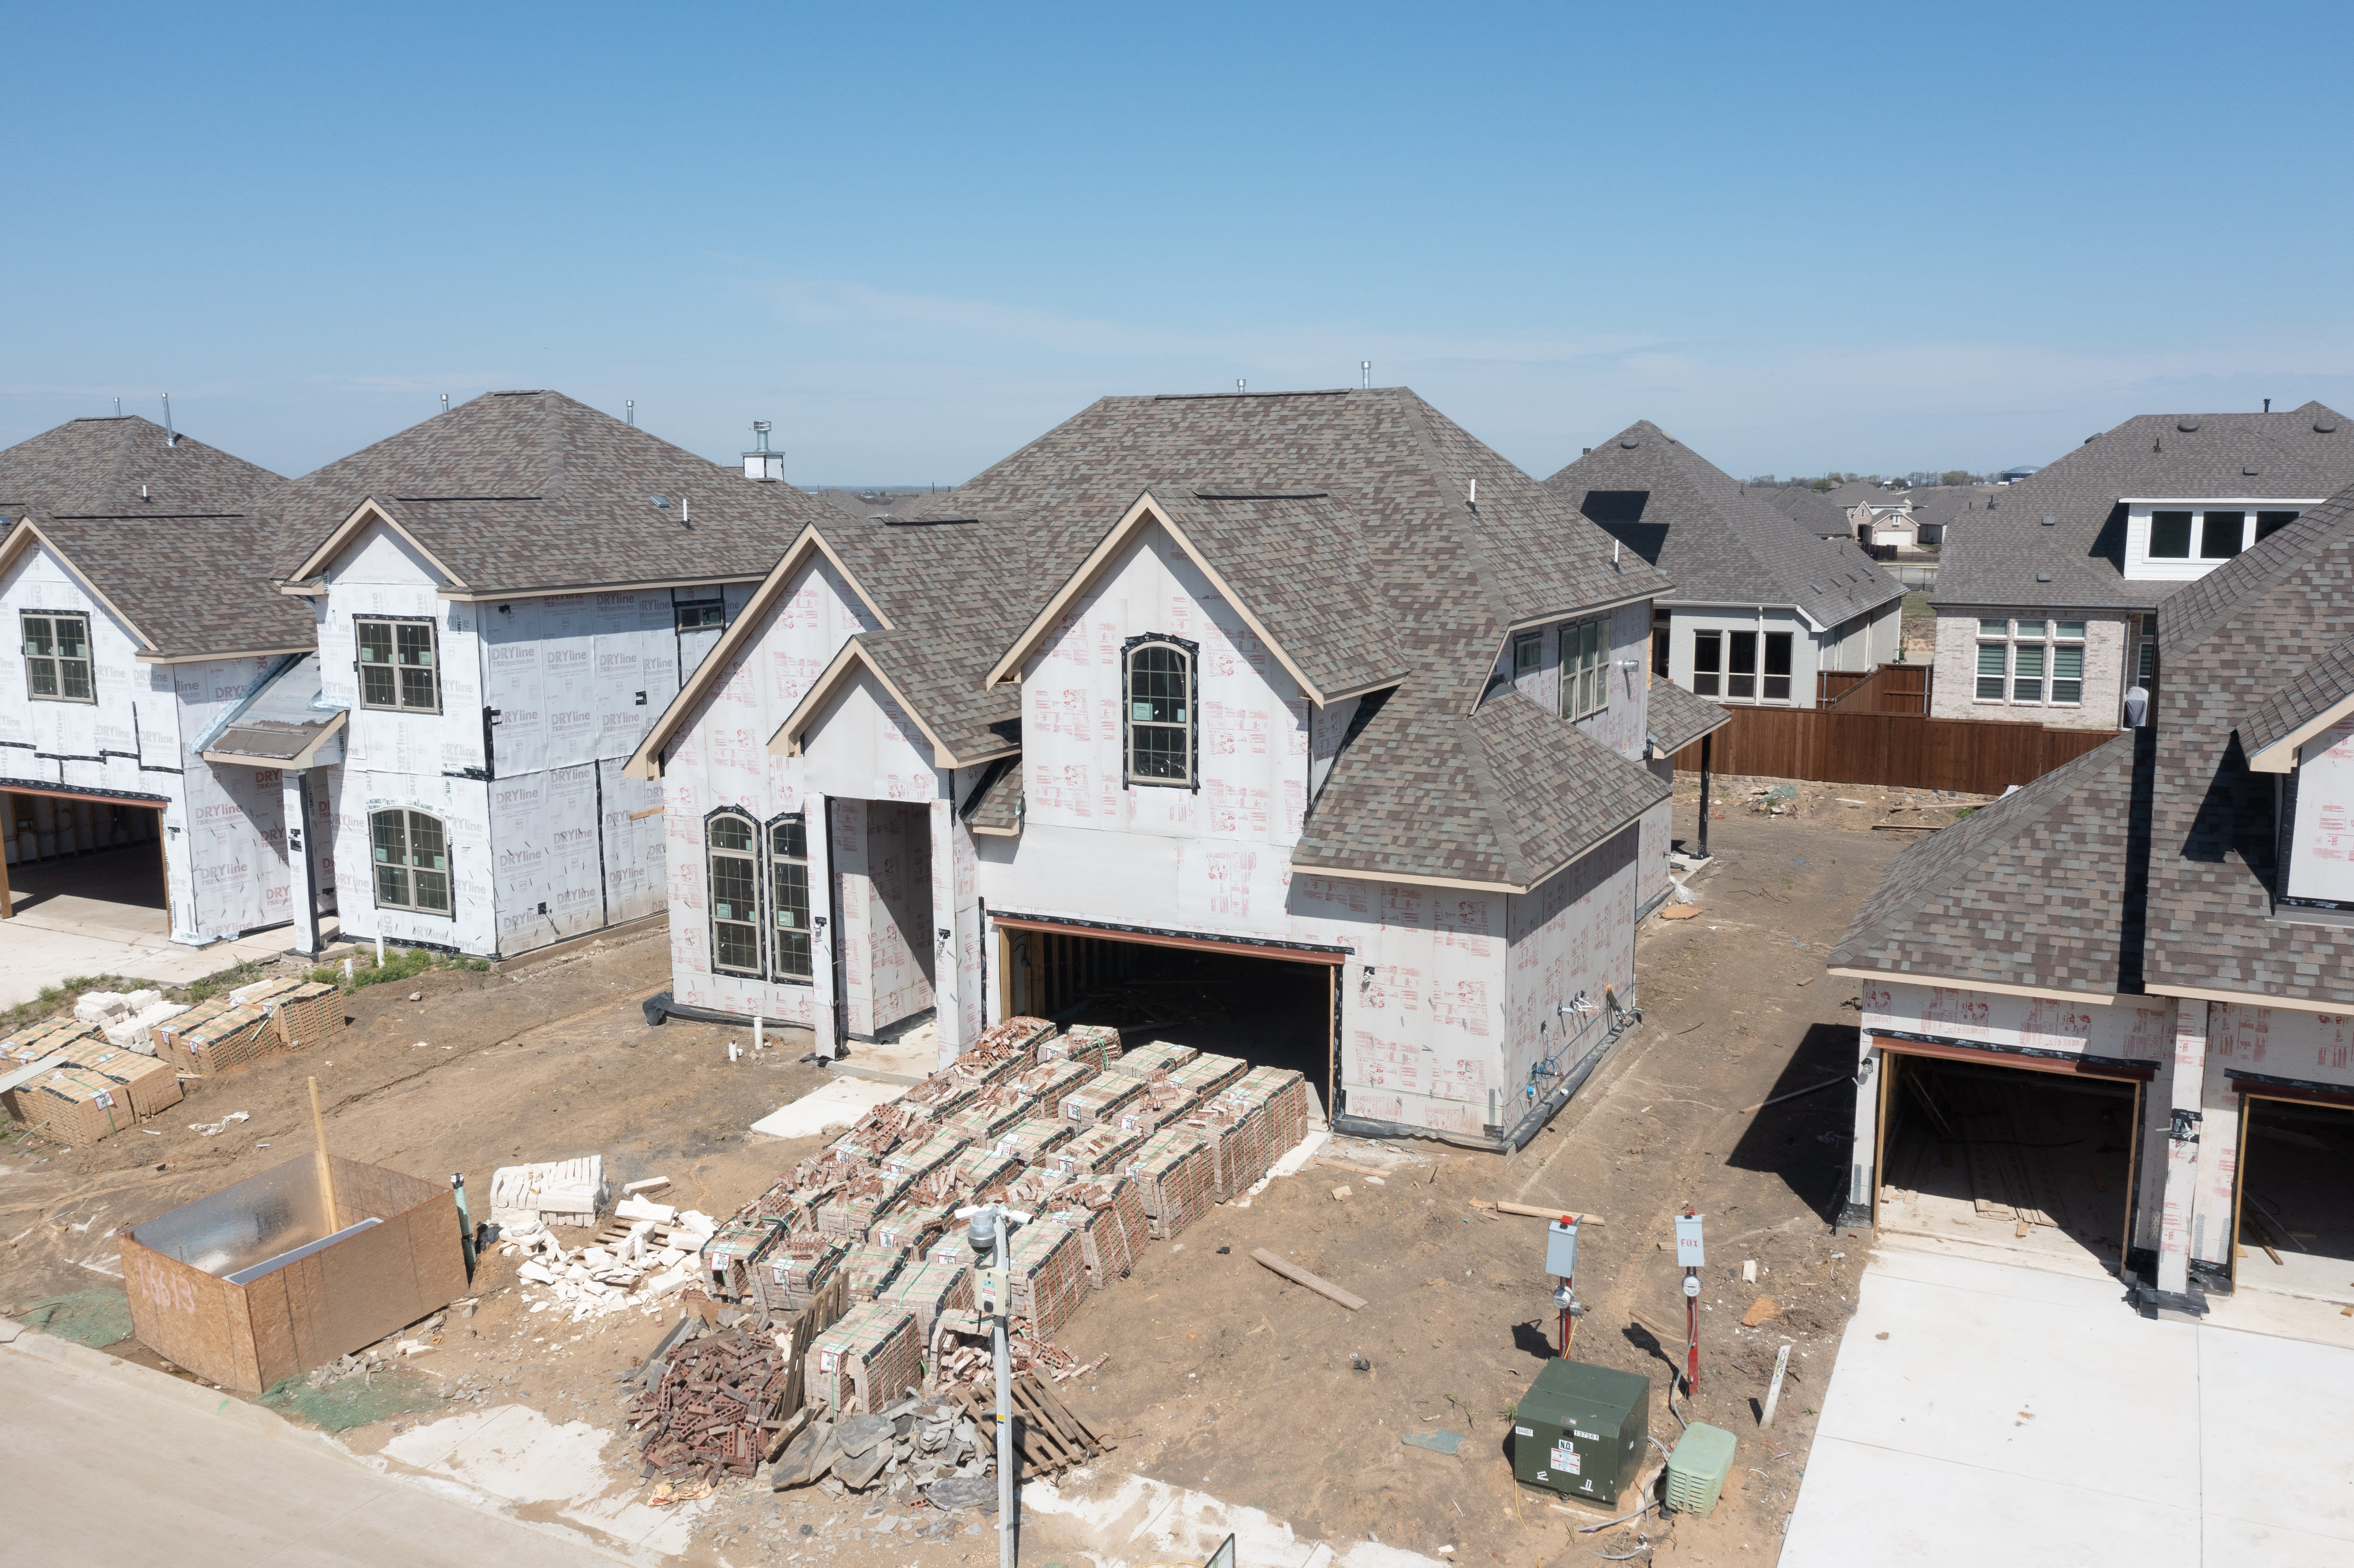
Both towns have a wave of new construction moving through right now — large master-planned communities in Van Alstyne along the US-75 corridor, and similar builder-driven growth in Anna as the Metroplex pushes north. That matters for rate-sensitive buyers for one specific reason: national production builders (the kind building in both towns) are far more willing than an individual resale seller to buy your rate down.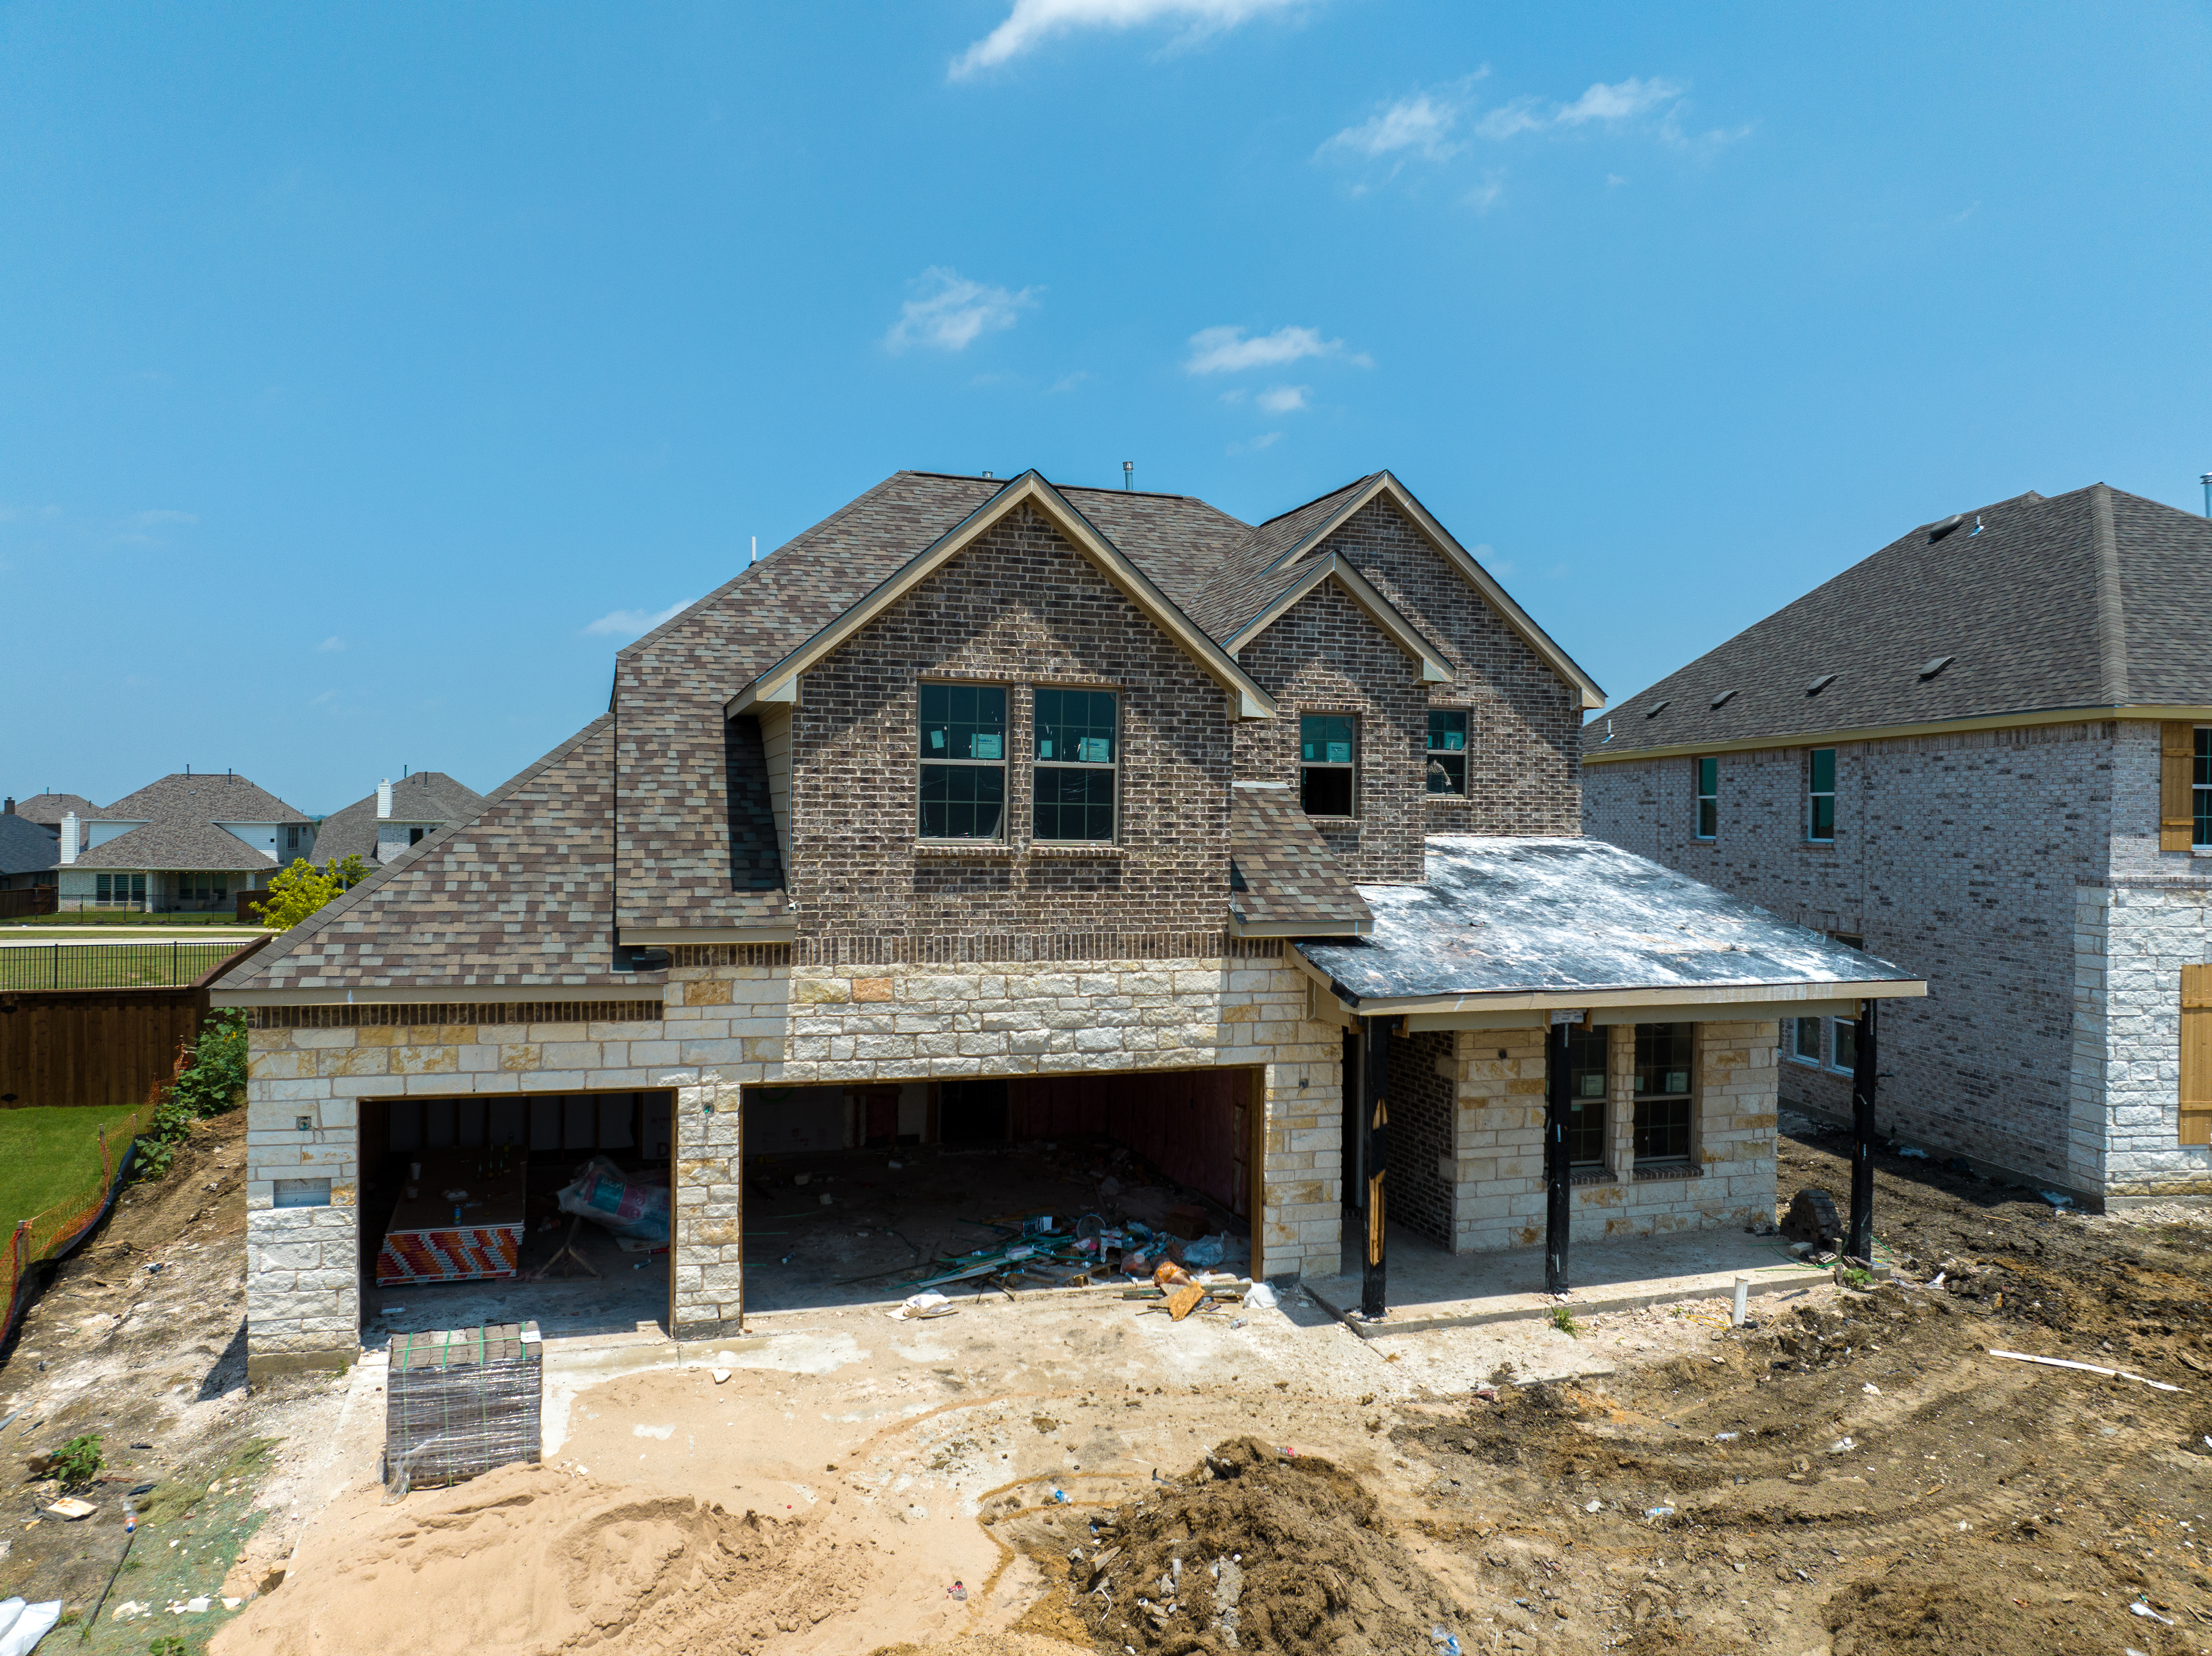
A temporary buydown — often structured as a 2-1, where your rate is reduced for the first year, less in the second, then reverts to the note rate in year three — can meaningfully soften a payment in year one while you get settled. A permanent buydown, where the builder pays points upfront to lower your rate for the life of the loan, is a different tool that makes more sense if you're planning to stay put for a long time. Neither is automatically the better deal — it depends on your timeline, your down payment, and whether the builder quietly built the cost of the incentive into the home price. It's worth running the actual numbers side by side rather than judging a deal by the headline rate alone.
This is exactly where a resale home can lose out to new construction right now, even at a similar price point — a private seller generally isn't in a position to buy your rate down the way a builder with in-house lending can.
What I'd actually tell a buyer right now
Don't wait for a “perfect” rate. Rates bouncing in the mid-to-high 6% range isn't unusual for this market, and there's no strong signal they're about to drop meaningfully before spring. If a home works for your budget at today's rate, that's the number to plan around — you can always look at refinancing later if rates ease.
If you're looking at new construction, ask about the buydown math up front. Get the builder's preferred-lender rate and an outside lender's rate side by side, including any price premium tied to using their lender. The better deal isn't always the one with the lower headline rate.
Get pre-approved before you fall in love with a house. With rates moving, your pre-approval number can shift week to week. It's a five-minute conversation with a lender that saves you from chasing a home you can no longer comfortably afford.
Don't ignore resale just because new construction has flashier incentives. An established home in Van Alstyne or Anna without HOA fees stacked on top, or one that's been on the market long enough for a seller to be motivated on price, can still out-perform a new build once you run the full comparison — not just the interest rate.
Rate headlines change week to week, but the fundamentals of buying smart in this area don't. If you want to talk through what a specific rate move actually does to your numbers on a home you're considering — new construction or resale — I'm glad to walk through it with you.
Search Van Alstyne homes · Search Anna homes · Talk with Kelly about your search